Burnaby has a mix of long-held family homes and a lot of condos around Metrotown, Brentwood and Edmonds. A typical single-family home is assessed at about $1.96 million for 2026, and a typical strata home at about $706,000. Both can work for a reverse mortgage, but they are treated quite differently.
Burnaby at a glance
| Typical 2026 BC Assessment value | Value | Change from 2025 |
|---|---|---|
| Single-family home | $1,959,000 | -4% |
| Strata (condo or townhouse) | $706,000 | -4% |
Typical assessed values as of July 1, 2025, published by BC Assessment for 2026. Your home's market value and a lender's appraisal can differ.
A couple whose youngest is 72, with a typical Burnaby house worth $1,959,000, would see roughly $725,000 to $827,000 on our calculator (location set to "Vancouver, Victoria, Kelowna area").
Illustration only. Not a quote, offer or approval. Any existing mortgage is paid out first, so your cash in hand is less. Try your own numbers in the calculator.
What to know about reverse mortgages in Burnaby
Condo owners: expect a lower percentage
Lenders typically lend a lower share of value on condo apartments than on houses. On a typical $706,000 Burnaby strata home, a couple whose youngest is 72 would see roughly $230,500 to $263,500 on our calculator. Some lenders also have rules about building age, size or type, so check before you plan around it.
Strata fees and special levies still have to be paid
A reverse mortgage removes mortgage payments. It does not remove strata fees, special levies, property taxes or insurance. If your building is older and big repairs are coming, plan for those costs first.
Long-time house owners
For owners of older Burnaby houses, the bigger question is often stay or sell. With new rules allowing more homes on many single-family lots, some families look at redeveloping with family or adding a suite. A reverse mortgage can bridge the gap while you decide, or let you stay put for good.
The basics, in one minute
A reverse mortgage lets homeowners 55 and over borrow against their home with no regular payments required on most products. You keep title. Interest is added to the balance, so the amount owed grows and the equity left shrinks. The loan is repaid when the home is sold, the last borrower moves out for good or passes away, or the loan goes into default. You must keep paying property taxes and insurance and keep the home in good repair. Rates are typically higher than a regular mortgage, and fees apply. Read the full BC guide or the honest pros and cons.
If a spouse is not on the loan, it can come due when the borrowing spouse dies or moves out, even if that spouse still lives in the home. Check this in writing before signing.
Alternatives worth comparing in Burnaby
- A HELOC, if you qualify and can handle monthly payments
- BC property tax deferment, if the tax bill is the main pressure
- Renting a suite or room, if the home and local rules allow it
- Family help, if everyone agrees and can afford it
- Downsizing, if the home no longer fits
If a cheaper tool solves the problem, use that one. I will tell you straight if a reverse mortgage is the wrong move.
Other BC cities
Questions people ask
How much can I get with a reverse mortgage in Burnaby?
On a typical $1.96 million Burnaby house, a couple whose youngest is 72 would see roughly $725,000 to $827,000 on our calculator. On a typical $706,000 strata home, roughly $230,500 to $263,500. Illustrations only.
Can I get a reverse mortgage on a Burnaby condo?
Often, yes. Expect a lower percentage than on a house, and keep strata fees and levies paid.
Do I still pay strata fees with a reverse mortgage?
Yes. Strata fees, special levies, property taxes and insurance all stay with you.
About the author
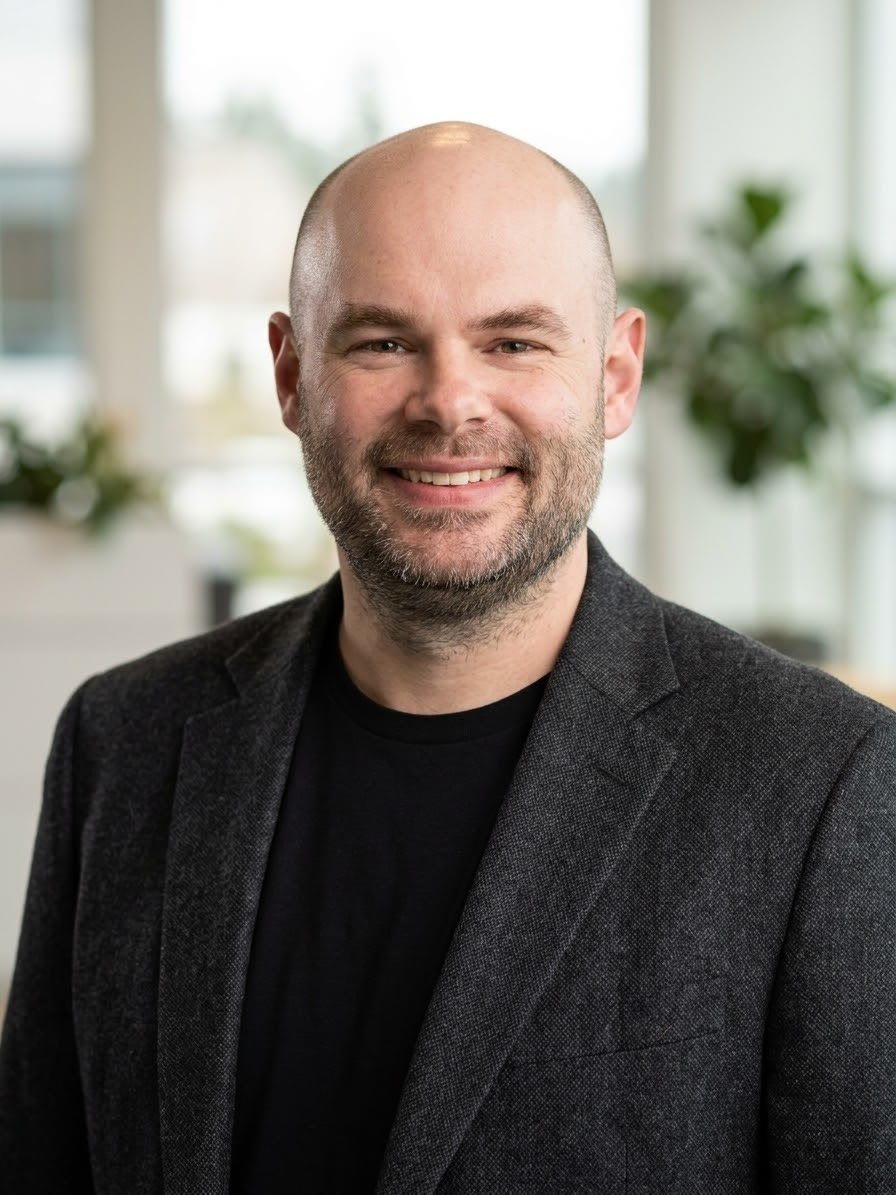
Matt Blake is a licensed mortgage broker in British Columbia with BRX Mortgage Inc. He helps homeowners 55 and over, and their families, compare reverse mortgages with HELOCs, selling and downsizing, and he will tell you straight when a reverse mortgage is the wrong move.
Licence MB600487 · BRX Mortgage Inc., brokerage licence X301291 · Last reviewed October 2026
Want your own numbers?
Get a free BC Equity Report built for your home and your age. It is an estimate, not a lender quote, and there is no obligation.